
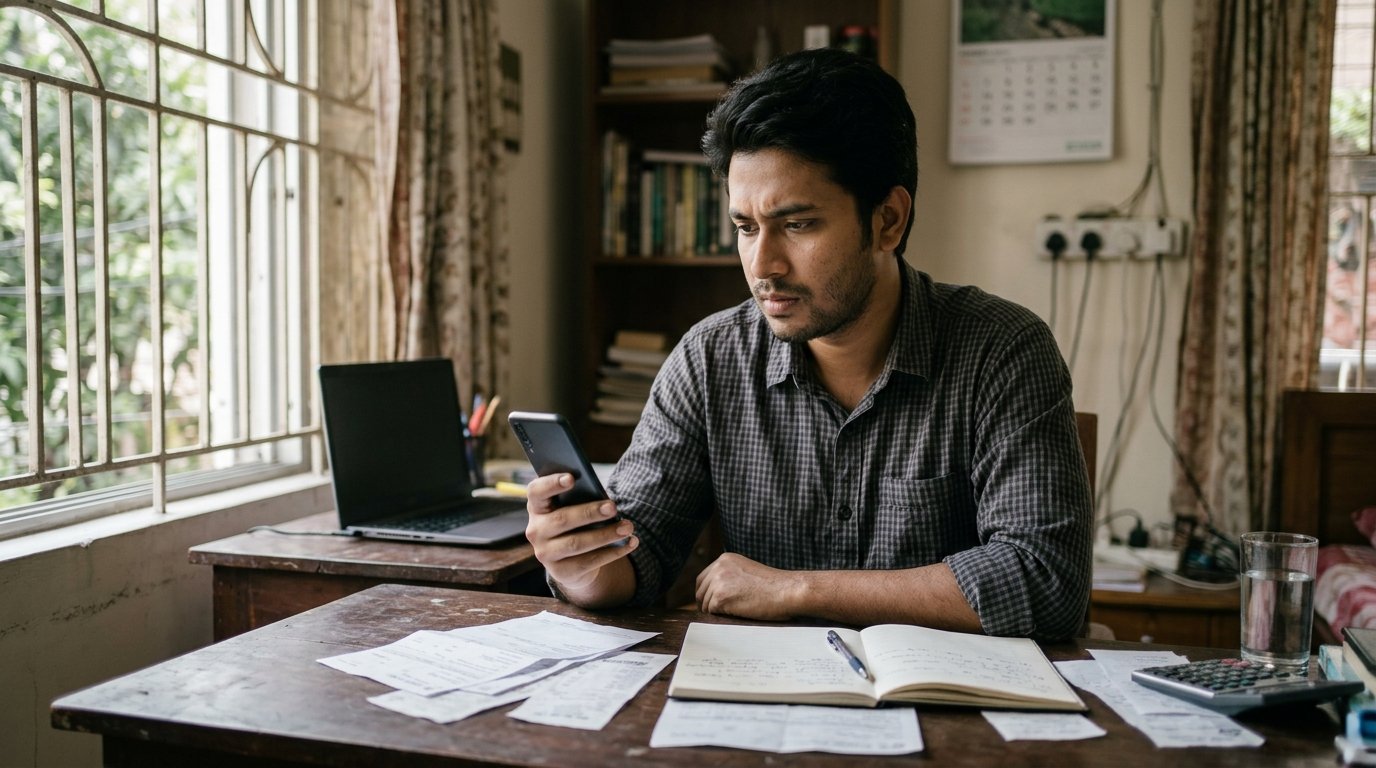
It’s the 28th. You glance at your phone and your balance stops you cold. Payday felt like a fresh start. This time, you told yourself, you’d save something. But somehow it’s all gone, and you can’t even remember where.
This isn’t just your story. And it isn’t because you’re lazy or careless. It’s because you’re human.
The Problem Isn’t Willpower
We tend to believe we can’t save because we lack “discipline.” Behavioral economics tells a different story.
In 2001, Brigitte Madrian and Dennis Shea published a now-famous study. At one company, employees had to fill out a form to join the retirement savings plan, and participation hovered around 37%. When the rules changed so that everyone was enrolled automatically (with the option to opt out), participation jumped to roughly 86%.
People didn’t suddenly become more responsible. The decision just stopped needing to be made every day. Whatever the system sets as the default, people tend to follow.
Here’s the core lesson: if good money habits depend on your memory, you’ll lose. If they’re built into a system, you’ll win.
Step 1: Pay Yourself First
It’s an old idea, but it works. “I’ll save whatever is left after spending” almost never succeeds, because spending expands to match whatever money is in your hand.
Flip it. On payday (or the morning after), have a fixed portion move automatically into a separate account. Starting with 10% is great. 20% is better. If that’s too much, begin with 5%. The number matters less than the start.
A standing instruction at your bank, a scheduled transfer in your mobile banking app, or a monthly deposit scheme: whichever suits you is the right one. Set it once, then forget it.
Step 2: Automate the Increase Too
Economists Richard Thaler and Shlomo Benartzi designed a plan called “Save More Tomorrow.” The idea is simple: employees don’t raise their savings today, but whenever a future raise arrives, part of it flows into savings automatically.
The results were striking. Participants’ average savings rate climbed from about 3.5% to about 13.6% over roughly forty months. A raise doesn’t feel like a loss when you never held that money in your hands in the first place.
You can do this on your own. Every time you get an increment or extra income, make a rule: half of the extra goes to savings, half to your lifestyle.
Step 3: Give Your Money Separate “Homes”
When all your money sits in one account, all of it feels like spending money. So divide it by purpose:
– Daily spending: The account or wallet you use every day holds only what you need for the month.
– Emergency fund: Three to six months of essential expenses, for job loss, illness, or sudden trouble. Keep it out of easy reach, but accessible when truly needed.
– Goal-based savings: Marriage, a pilgrimage, a home, your child’s education, whatever your dream is. Give each goal its own name.
– Investments: For long-term growth. Where you invest depends on your goals and risk tolerance. Never put money in because of hype or someone’s say-so, and treat promises of unusually high returns with deep suspicion.
Naming has real psychological power. It’s much easier to withdraw from an account labeled “Savings” than from one labeled “Mom’s Medical Fund.”
Step 4: Add Friction to Spending, Remove It from Saving
We do what’s easy. If your card is saved in a shopping app, one tap completes the purchase. If it isn’t, the urge often fades before you’ve typed in the number.
A few small moves help:
– Delete saved cards and wallet details from shopping apps.
– Cancel subscriptions you don’t use. Small monthly charges add up to big yearly sums.
– Keep your savings account at a bank whose app you don’t open daily.
– Adopt a 24-hour waiting rule before any big purchase.
Step 5: Spend 15 Minutes a Month, Not More
Automation doesn’t mean neglect. Once a month, on a fixed day, sit down for 15 minutes and ask three questions:
1. Did my automatic transfers go through properly?
2. Which expense this month was unnecessary?
3. Has my income grown? If so, can I raise my savings rate too?
That’s it. No need to obsess over daily tracking. The system works for you; you just adjust the direction now and then.
A Truth Nobody Tells You
An automatic system won’t make you rich overnight. If your income is lower than your expenses, no system can work magic. In that case, you’ll first need to find ways to cut costs or raise income.
But if even a small amount is left over, this system will slowly turn it into a solid foundation. And that’s where the real power of compound interest lies: time. Someone who starts today with 500 taka is far ahead of someone who waits five years to “start with a big amount.”
The person you were a few years ago may have asked something of you: a little security, a little peace, the courage to sleep soundly. You can’t help that person today. But today’s you can help the you of five years from now. You don’t need to do anything big. Pick up your phone right now, open your banking app, and set up one small automatic transfer. It takes five minutes.
Because being wealthy doesn’t always mean earning more. Often, it means having a system that keeps working for you even while you sleep. Your small decision today is tomorrow’s big freedom.