
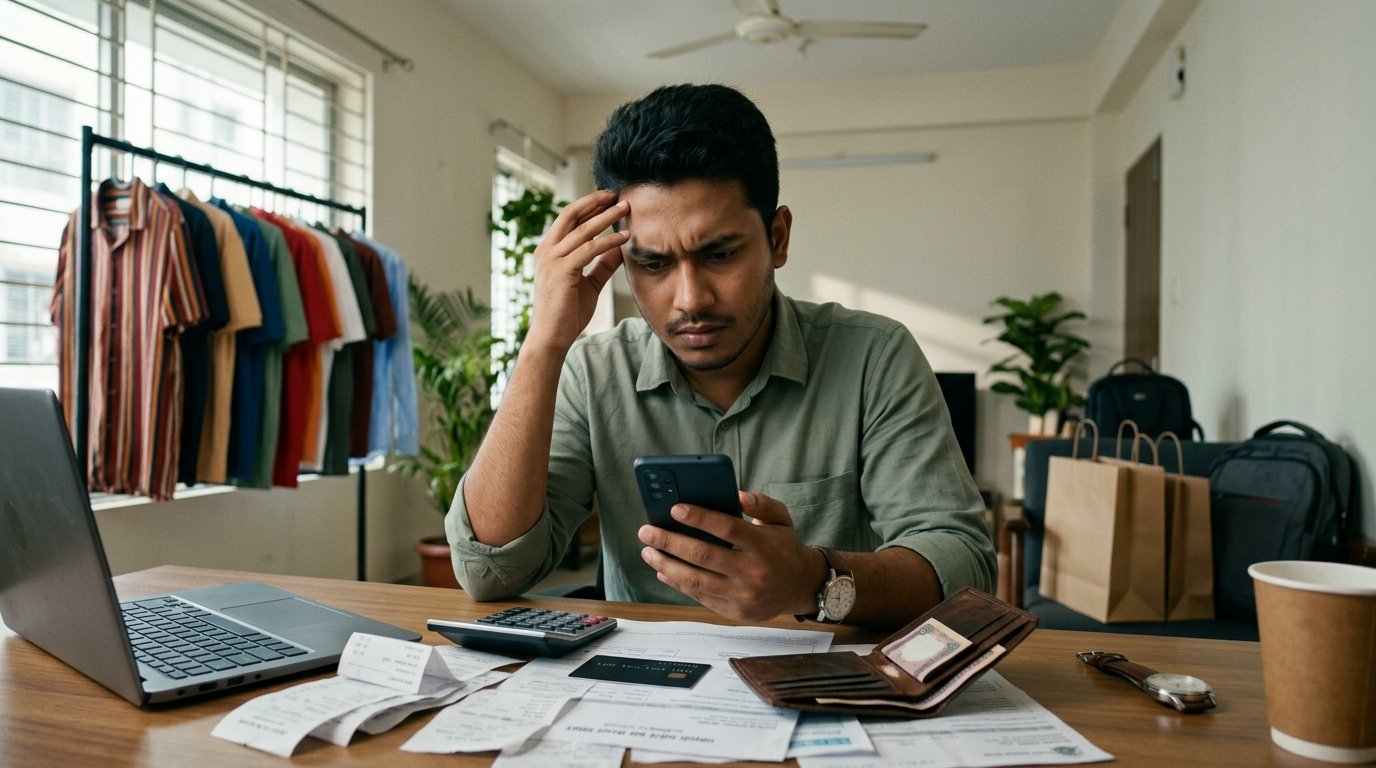
Have you ever looked at your bank balance at the end of the month and thought, “My income is higher than last year, so why is there nothing left?”
You’re not the only one asking. When your first salary arrived, it felt like you had conquered the world. Then came the increment, the promotion, and your income doubled. But your savings? They stayed right where they were, or even shrank. The problem isn’t your income. It’s a silent habit called lifestyle inflation.
What Is Lifestyle Inflation, Really?
Lifestyle inflation, sometimes called “lifestyle creep,” means raising your spending standard every time your income rises. When your salary goes up, it’s natural to eat a little better, dress a little better, live a little better. The trouble is that “a little better” slowly becomes “this is my bare minimum.”
This isn’t price inflation, where the cost of goods rises in the market. Here, we are the ones raising the price, by raising the standard of our own demands.
Silent, Because Nobody Notices
The dangerous thing about lifestyle inflation is that it never arrives as one big decision. It comes in small moments of “it’s fine, I can afford this much.”
– Eating out once a week becomes eating out four days a week.
– A basic phone becomes a new flagship every two years.
– Rickshaws and buses give way to regular ride-sharing.
– More subscriptions than you need, half of which you never use.
– Clothes, watches, and gadgets bought because you “have to look the part.”
Each expense looks harmless on its own. Together they form a huge current that sweeps away every bit of your extra income.
What Does the Research Say?
Behavioral economics has been studying this for many years.
Hedonic adaptation: Psychologists call it the “hedonic treadmill.” We feel happy when we get something new, but soon it becomes normal and our happiness returns to its old level. Then we reach for the next new thing. In other words, spending more can’t buy lasting happiness.
Income and happiness: Well-known research by Nobel laureate Daniel Kahneman and Angus Deaton found that once basic needs are met, rising income doesn’t raise day-to-day happiness proportionally. Later studies have debated this, but the core lesson stands: more income doesn’t automatically mean more contentment.
The reality for consumers: Surveys in the United States have repeatedly shown that even many high earners run out of money before the month ends. There is no automatic rule that higher income means higher savings. The same pattern shows up among young middle-class professionals in our own country: EMIs, credit cards, and hobby expenses claim a large share of the salary before the month even begins.
Social comparison: We set our own standards by looking at other people’s curated lives on Facebook and Instagram. Researchers call this “relative deprivation”: what unsettles us isn’t how we are doing, but how we are doing compared to others. And we spend to soothe that restlessness.
See How Big the Damage Is
Suppose your monthly income is 30,000 taka and you save 3,000. Two years later, your income rises to 50,000. If you spend the entire extra 20,000, your savings remain that same 3,000.
Now look at the alternative. If you put half of the extra income, 10,000 taka, into an investment or savings certificate earning 8 percent a year, it would grow to roughly 18 lakh taka in 10 years (compounded, an approximate figure). You only saved half. With the other half, you still enjoyed your life.
That is the difference. One person earns more and ends up empty-handed. Another, on the same income, moves steadily toward financial freedom.
How to Recognize the Trap
Ask yourself these questions:
1. Over the last three years, how much has my income grown, and how much have my savings grown?
2. If one month’s salary didn’t arrive, how long could I manage?
3. How many items on my monthly expense list didn’t exist two years ago?
4. When I buy something, am I thinking “I need this” or “everyone has this”?
If the answers make you uncomfortable, the silent thief has already moved into your house.
Practical Ways to Escape
1. Pay yourself first. The moment your salary arrives, set aside your savings. Live on what’s left. Doing it the other way around, trying to save whatever remains after spending, leaves nothing.
2. The 50 percent increment rule. Each time your income rises, send at least half of the increase to savings or investment. Reward yourself with the other half. You won’t feel deprived, and your future stays protected.
3. Automate it. Set up a standing instruction with your bank so money moves to a savings account on payday. Relying on a system works far better than relying on willpower.
4. Subscription audit. At least twice a year, review all recurring expenses. Cancel anything you didn’t use last month.
5. The 24-hour rule. Before any unplanned big purchase, wait one day. Often the urge has vanished by the next morning.
6. Compare less. Don’t measure your behind-the-scenes life against someone else’s highlight reel. Your financial goals are your own, not anyone else’s.
Does This Mean Becoming a Miser?
Not at all. The answer to lifestyle inflation isn’t giving up all joy. It’s choosing consciously: which expense genuinely makes me happy, and which is just habit or show? Spend freely on what truly improves your life. And say goodbye to what gives you nothing except an empty hand at the end of the month.
Think about your parents for a moment. They may have run a household on a small income, educated their children, and still managed to put something aside. They may not have had so many investment apps or opportunities, but they had one understanding: you can’t spend all of today’s money today. Your earning opportunities today are greater than theirs. The question is simple: will that extra income set you free, or tie you to an ever-heavier lifestyle?
Ten years from now, standing in front of the mirror, you’ll be able to say one of two sentences: “I earned a lot, but saved nothing,” or “I set aside a part of what I earned for my own future.”
The time to choose that sentence is today. Because lifestyle inflation doesn’t come shouting. It comes quietly, hand in hand with every “it’s fine, I can afford this much.” If you don’t stop it today, tomorrow it will eat your dreams. May your income grow, but may your savings grow even faster.